Planning Ahead: How to Calculate Future Healthcare Expenses for Retirement


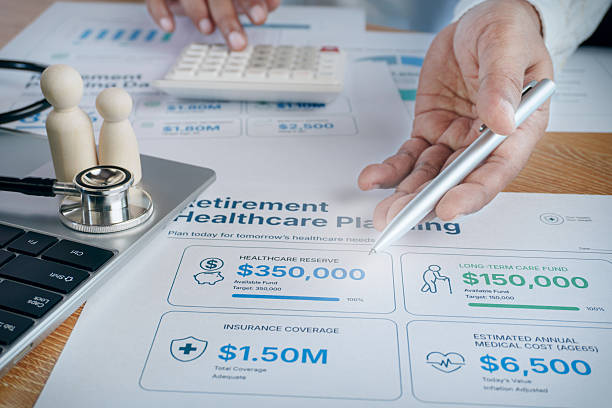
Retirement offers an opportunity to enjoy life without the daily demands of work. However, maintaining financial security requires careful planning, especially when healthcare expenses increase with age. Medical appointments, prescription medications, insurance premiums, and unexpected treatments can affect retirement savings. Therefore, understanding future healthcare expenses helps individuals prepare financially and avoid unnecessary stress during retirement.
Moreover, estimating healthcare costs involves more than reviewing current medical bills. Individuals must consider inflation, changing health conditions, insurance coverage, and possible long-term care needs. Without proper preparation, unexpected expenses may disrupt retirement plans. Consequently, developing realistic financial estimates allows future retirees to protect their savings and make informed decisions about their healthcare needs.
Understanding Common Healthcare Expenses During Retirement
Healthcare expenses during retirement include several types of medical services and treatments. Routine doctor visits, prescription medications, specialist consultations, dental care, and vision services can create regular financial obligations. Additionally, some retirees may require medical equipment, physical therapy, or ongoing treatment for chronic conditions. Therefore, identifying these expenses provides a useful starting point for estimating future healthcare costs.
Furthermore, medical spending varies depending on personal health, lifestyle, geographic location, and insurance coverage. Some individuals require limited medical attention, while others need frequent appointments and specialized treatments. Consequently, reviewing previous healthcare expenses can help identify spending patterns. Individuals should also consider possible changes in their medical needs as they grow older.
Reviewing Current Medical Spending and Health Conditions
A practical healthcare estimate begins with examining current medical expenses. Individuals should review insurance statements, pharmacy receipts, hospital bills, and regular treatment costs. Additionally, they should calculate annual spending on services their insurance does not fully cover. Therefore, organizing these records helps establish a realistic starting point for future healthcare planning.
Moreover, existing health conditions can influence future medical expenses. Individuals managing diabetes, arthritis, heart conditions, or other chronic illnesses may need regular treatment and medication. However, even healthy adults can experience unexpected medical problems during retirement. Consequently, financial estimates should reflect current healthcare needs while allowing room for changes that may occur later.
Understanding Medicare and Other Insurance Coverage
Health insurance plays an important role in determining retirement healthcare expenses. In the United States, Medicare provides coverage for many eligible adults beginning at age 65. However, beneficiaries may still pay premiums, deductibles, copayments, and coinsurance. Therefore, understanding these financial responsibilities helps individuals estimate how much money they may need for medical services.
Additionally, retirees should compare available Medicare coverage options and any employer-sponsored retiree benefits. Medicare Advantage plans, Medicare Supplement Insurance, and prescription drug coverage may affect total healthcare spending differently. Consequently, reviewing plan details helps individuals identify potential coverage gaps. Future retirees should also consider healthcare coverage before Medicare eligibility if they plan to leave the workforce early.
Estimating Prescription Medication and Treatment Costs
Prescription medications can represent a significant portion of retirement healthcare spending. Individuals with chronic conditions may require daily medications, regular laboratory tests, or specialist appointments. Additionally, medication prices and insurance benefits can change over time. Therefore, reviewing current prescriptions and discussing possible future needs with healthcare professionals can improve financial estimates.
Furthermore, retirees should examine their prescription drug coverage and understand potential out-of-pocket expenses. Some medications may have lower-cost generic alternatives when medically appropriate. However, individuals should consult healthcare providers before changing prescribed treatments. Consequently, comparing available pharmacy options and reviewing insurance benefits can help manage expenses while maintaining appropriate medical care.
Accounting for Healthcare Inflation Over Time
Healthcare expenses may increase throughout retirement because of inflation and changes in medical service costs. Insurance premiums, professional care fees, and certain treatments may become more expensive over time. Additionally, retirees may need more frequent healthcare services as they age. Therefore, financial estimates should consider potential price increases rather than rely entirely on current spending.
Moreover, individuals can use different inflation assumptions to understand possible future expenses. For example, an annual healthcare budget of $5,000 would increase to approximately $7,400 after 20 years with a 2% yearly increase. However, actual healthcare inflation may differ significantly. Consequently, reviewing estimates regularly helps future retirees maintain realistic savings targets.
Preparing for Long-Term Care and Assisted Living Expenses
Long-term care can create substantial financial responsibilities during retirement. Some individuals may eventually need assistance with bathing, dressing, mobility, or other everyday activities. These services may involve home caregivers, assisted living communities, or nursing facilities. Therefore, estimating potential long-term care expenses helps individuals prepare for financial needs that extend beyond routine medical treatment.
Furthermore, Medicare generally does not cover ongoing custodial long-term care. Medicaid may help eligible individuals pay for certain services, depending on state requirements. However, coverage limitations and eligibility rules can affect available assistance. Consequently, future retirees should research local care costs, explore insurance options, and consider how personal savings could support possible care needs.
Creating a Realistic Healthcare Savings Target
After estimating future medical expenses, individuals can establish a healthcare savings goal. This target should consider expected insurance premiums, regular medical appointments, medications, and potential unexpected treatments. Additionally, individuals should compare projected healthcare spending with expected retirement income. Therefore, calculating the difference helps determine how much additional money they may need to save.
Moreover, retirement savings targets should reflect personal circumstances rather than general assumptions. A person retiring at 60 may face different healthcare expenses than someone retiring at 67. Similarly, family health history and existing medical conditions may influence planning decisions. Consequently, reviewing individual circumstances helps create more practical savings goals that support long-term financial stability.